

There are two oil prices on your screen, but most headlines treat them as if they represent the same barrel. They actually don’t.
Oil fell sharply earlier this week, with Brent settling near $98 and WTI closing around $90 by Wednesday.
Several catalysts drove the declines, but these didn’t affect both benchmarks equally. Some were mainly Brent stories, while one barely qualifies as an oil story at all.
So What Are WTI and Brent, Anyway?
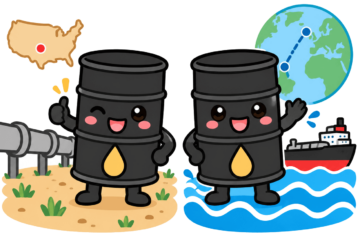 West Texas Intermediate, or WTI, is the benchmark for U.S. crude. Its price is based on oil delivered to Cushing, Oklahoma, a landlocked storage and pipeline hub in the middle of the country.
Moving that crude to an export terminal requires pipeline transportation, which typically costs a few dollars per barrel. That’s one structural reason Brent normally trades above WTI.
Brent is the global crude benchmark. Its price is based on North Sea grades known as BFOET, which stands for Brent, Forties, Oseberg, Ekofisk, and Troll. Unlike WTI stored at Cushing, Brent can be loaded directly onto tankers and shipped almost anywhere in the world.
Roughly two-thirds of internationally traded crude is priced against Brent.
Both grades are light, sweet crude, meaning they have low sulfur content and are easy to refine into gasoline and diesel. WTI is slightly lighter and sweeter, but the quality difference is small. Geography and logistics explain most of the price gap.
The two benchmarks also trade on different clocks. Brent’s deepest liquidity typically runs from 9:00 a.m. to 3:00 p.m. GMT, while WTI trading is more closely tied to New York hours. Brent’s overnight session reopens at 8:00 p.m. Eastern, two hours after WTI
So, if a headline lands during that gap, the two contracts may not react at the same time.
Promoted: Trade the Signal, Not Just the Headline.
WTI and Brent can react differently to the same oil news, sending CAD and NOK down separate paths. Once you’ve identified which benchmark matters, FTMO gives you a structured way to test your strategy with no time limits, free trials, and up to $200K in Demo Capital.
Disclosure: To help support our content, we may earn a commission from our partners if you sign up through our links, at no extra cost to you.
Which Headlines Move Brent, and Which Move WTI?
This week gave traders a useful set of real-world examples:
SPR release and diesel ban: WTI stories. The U.S. Department of Energy offered up to 40 million barrels from the Strategic Petroleum Reserve, or SPR, the government’s emergency crude stockpile. That supply enters the domestic market, putting pressure on WTI first.
A proposed U.S. diesel export ban adds another layer. Keeping more diesel inside the country could weaken WTI-linked refining economics while reducing supplies available to Europe. Analysts estimate the policy could lower U.S. diesel prices by roughly 4% while raising costs across Europe.
Europe and the IEA have also coordinated reserve releases, putting pressure on Brent from their side. Still, the domestic supply boost hits the WTI market first.
Russia sanctions: a Brent story. Reports emerged that President Trump supports easing sanctions on Russia in exchange for political prisoner releases, potentially opening the door to deals involving Russian oil and diesel.
Russian crude flows into seaborne markets, not Cushing. If those barrels return to international trade, they would add to the global supply reflected in Brent prices. WTI could still feel pressure through the broader crude market, but not through its own delivery chain.
Persian Gulf export recovery: another Brent story. Analysts estimated that Gulf oil exports recently recovered to their 2025 average, including dark shipments carried by vessels that obscure the origins of their cargo.
Saudi Arabia led the rebound, while Iran officially shipped no crude by sea during the period. Saudi Arabia has rerouted shipments through the East West Pipeline to Yanbu, bypassing Hormuz and adding to seaborne supply. Meanwhile, Iran’s lack of official sea exports suggests the disruption may already be priced into Brent rather than representing a fresh catalyst.
Dyed diesel eligibility: neither. Several U.S. states have expanded eligibility for dyed diesel, a lower-taxed fuel reserved for agriculture and other off-road uses. This changes who pays the tax. It doesn’t change how much crude enters the market. Oil prices respond to supply and demand, not which drivers get a tax break.
Why Does the Spread Matter for Forex Traders?
WTI and Brent affect commodity currencies differently, which can trip up traders who treat oil as one uniform signal.
CAD is more closely tied to WTI. Canadian heavy crude is priced at a discount to WTI, making it the more relevant benchmark for the Canadian dollar. Wednesday offered a clear example. WTI gained roughly 1.9%, but CAD still weakened — partly on broad dollar strength, and partly because the headline move was in Brent, not the benchmark CAD actually tracks.
NOK, or the Norwegian krone, has a more direct relationship with Brent. Norway exports North Sea crude into the same Atlantic Basin market. When the spread is wide, forces affecting Brent tend to weigh more heavily on NOK than on CAD.
For the U.S. dollar, WTI affects gasoline and diesel costs, which eventually feed into CPI and the Fed’s preferred PCE price index. Softer WTI following SPR releases could ease upward pressure on future inflation readings, which matters for near-term interest rate expectations.
Any credible sign that the Strait of Hormuz could reopen would probably hit Brent harder and faster than WTI, since Brent carries more of the current war premium. If that premium fades quickly, the spread could narrow sharply, and NOK could lose its oil advantage over CAD.
The Bottom Line
WTI and Brent don’t price the same thing. They’re both crude oil benchmarks, but WTI reflects U.S. supplies moving through a landlocked hub, while Brent reflects seaborne crude flowing through the global market.
The $8 spread is well above its one-year average of $5.00. Right now, three genuine supply developments and one tax story are affecting the benchmarks in very different ways.
CAD tends to follow WTI, while NOK tends to track Brent. When the spread widens, those currencies can diverge despite reacting to the same oil headlines. Before assuming a commodity currency will follow crude, check which benchmark is actually moving.
And remember, policy news appearing alongside supply news isn’t necessarily a supply story. Changing who pays a tax doesn’t change how many barrels are available. Crude markets price barrels. Spotting that difference can keep you from chasing a headline the market has already ignored.
This article explains why WTI and Brent affect CAD and NOK differently, a framework that’s easier to follow with the underlying oil-currency relationships in place. Premium members can read our lesson:
📖 How Oil Moves with USD/CAD, USD/NOK, and CAD/JPY
Reading this helps you understand why WTI and Brent affect CAD and NOK differently, how each pair’s structural link to crude is built, and how to use those relationships as confirmation signals when the two benchmarks diverge.
And if you’re not a Premium subscriber yet, now’s a good time to sign up.
With Babypips Premium, you get full access to School of Pipsology lessons that help you understand not just that oil is moving, but which benchmark matters for which currency and why the spread between WTI and Brent can send CAD and NOK in different directions.