

The 10-year Treasury yield touched 5.34% on Thursday, its highest since 2002, before easing toward 5.24%, and the S&P 500 recovered from a morning dip to trade a touch higher. The dollar gained against most majors, with the euro weakest, while the Swiss franc strengthened. Oil climbed about 3% as US-Iran talks stalled.
Check out the forex news and economic updates you may have missed in the latest trading session!
News Headlines & Data:
- U.S. Secretary of State Rubio ordered Iran’s UN delegation, including Foreign Minister Araghchi, to leave New York after talks stalled
- Fed Kashkari said inflation remains too high near 3% and that he has penciled in one more hike this year and another in 2027
- BOJ Summary of Opinions for the September meeting: some members said rate hikes may need to accelerate if prices overshoot 2%, while two favored holding because CPI was below 2%
- New Zealand Building Permits for August 2026: 5.6% m/m (0.9% m/m forecast; -4.3% m/m previous)
- Australia S&P Global Manufacturing PMI Final for September 2026: 49.6 (49.3 forecast; 52.0 previous)
- Japan S&P Global Manufacturing PMI Final for September 2026: 54.1 (55.2 forecast; 54.9 previous)
- U.K. Nationwide Housing Prices for September 2026: 0.8% y/y (1.5% y/y forecast; 1.6% y/y previous)
- Swiss Inflation Rate for September 2026: 1.0% y/y (1.0% y/y forecast; 0.8% y/y previous)
- Swiss Retail Sales for August 2026: 3.2% y/y (1.7% y/y forecast; 2.3% y/y previous)
- Swiss procure.ch Manufacturing PMI for September 2026: 55.3 (58.0 forecast; 57.1 previous)
- France S&P Global Manufacturing PMI Final for September 2026: 50.6 (50.3 forecast; 51.1 previous)
- Germany S&P Global Manufacturing PMI Final for September 2026: 53.9 (53.8 forecast; 54.3 previous)
- Euro area S&P Global Manufacturing PMI Final for September 2026: 52.9 (52.7 forecast; 52.7 previous)
- U.K. S&P Global Manufacturing PMI Final for September 2026: 51.9 (52.0 forecast; 51.7 previous)
- Euro area Unemployment Rate for August 2026: 6.4% (6.4% forecast; 6.4% previous)
- U.S. Challenger Job Cuts for September 2026: 43.28k (78.0k forecast; 52.88k previous)
- U.S. Initial Jobless Claims for September 26, 2026: 197.0k (195.0k forecast; 197.0k previous)
- Canada S&P Global Manufacturing PMI for September 2026: 51.5 (52.9 forecast; 53.0 previous)
- U.S. S&P Global Manufacturing PMI Final for September 2026: 55.9 (57.0 forecast; 53.9 previous)
- ISM Manufacturing PMI for September 2026: 54.5 (54.7 forecast; 54.6 previous)
Broad Market Price Action:
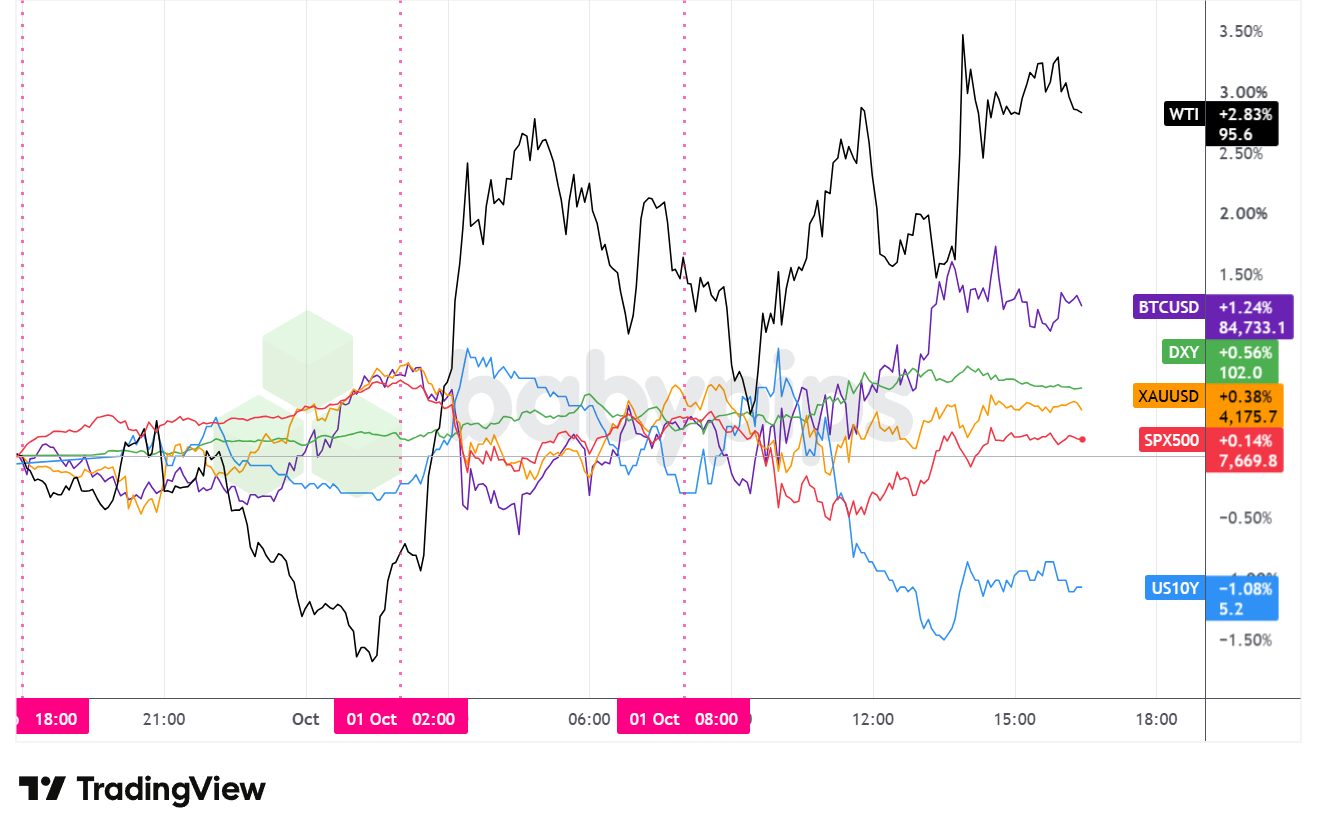
Dollar Index, Gold, Oil, S&P 500, U.S. 10-yr Yield, Bitcoin Overlay – Chart Faster With TradingView
The S&P 500 gained about 0.6% overnight to a peak near 7,707, a move that may reflect strength in chip stocks after Micron’s earnings lifted the Nikkei 225 by 2.5%. The index lost about 0.8% by 3:25 am ET as the 10-year yield climbed to 5.34%. At 10:00 am ET, the ISM Manufacturing prices index jumped to 77.9 against 71.3 expected, and the S&P 500 slid from near 7,650 to a low around 7,619 by 11:05 am ET. The index recovered as Treasury yields fell and traded near 7,670 late in the session, up about 0.1%.
WTI crude slid to near $91.40 at 1:25 am ET with no clear catalyst, reversed higher from about 2:30 am ET and climbed to around $95.50 by 4:50 am ET. One possible explanation is growing impatience with the US-Iran stalemate after Secretary of State Rubio ordered Iran’s UN delegation to leave New York. The geopolitical backdrop included a report that the Pentagon may soon send an additional aircraft carrier and 10,000 troops to the Middle East. WTI traded near $95.60 late in the session, up about 2.8%, after a high near $96.20 around 2:00 pm ET.
Gold bounced from a low near $4,140 at 8:30 pm ET on Wednesday to a high around $4,190 near 2:00 am ET, and fell about 0.8% by 3:25 am ET as yields climbed. Rising yields raise the opportunity cost of holding gold, which pays no interest. Gold slipped to around $4,154 after the ISM report and traded near $4,176 in late trading, up about 0.4%, below the $4,200 level it has struggled to reclaim.
Bitcoin dropped to a low near $83,160 at 4:30 am ET as yields held near 5.33%, and climbed to a high around $85,140 at 2:35 pm ET as the 10-year yield eased. Bitcoin changed hands near $84,700 late in the session, up about 1.2%. With no Bitcoin-specific news, the late gains may reflect better risk appetite as bond yield pressure eased.
The 10-year yield hovered near 5.28% overnight, climbed to its first 5.34% peak while oil rose, and traded near 5.24% in late trading, about 5 basis points below its starting level. Fed Vice Chair Jefferson said it may take more time to judge whether additional rate hikes are necessary, and an unwind of crowded positions and French fiscal worries potentially added to Treasury demand.
FX Market Behavior: U.S. Dollar vs. Majors
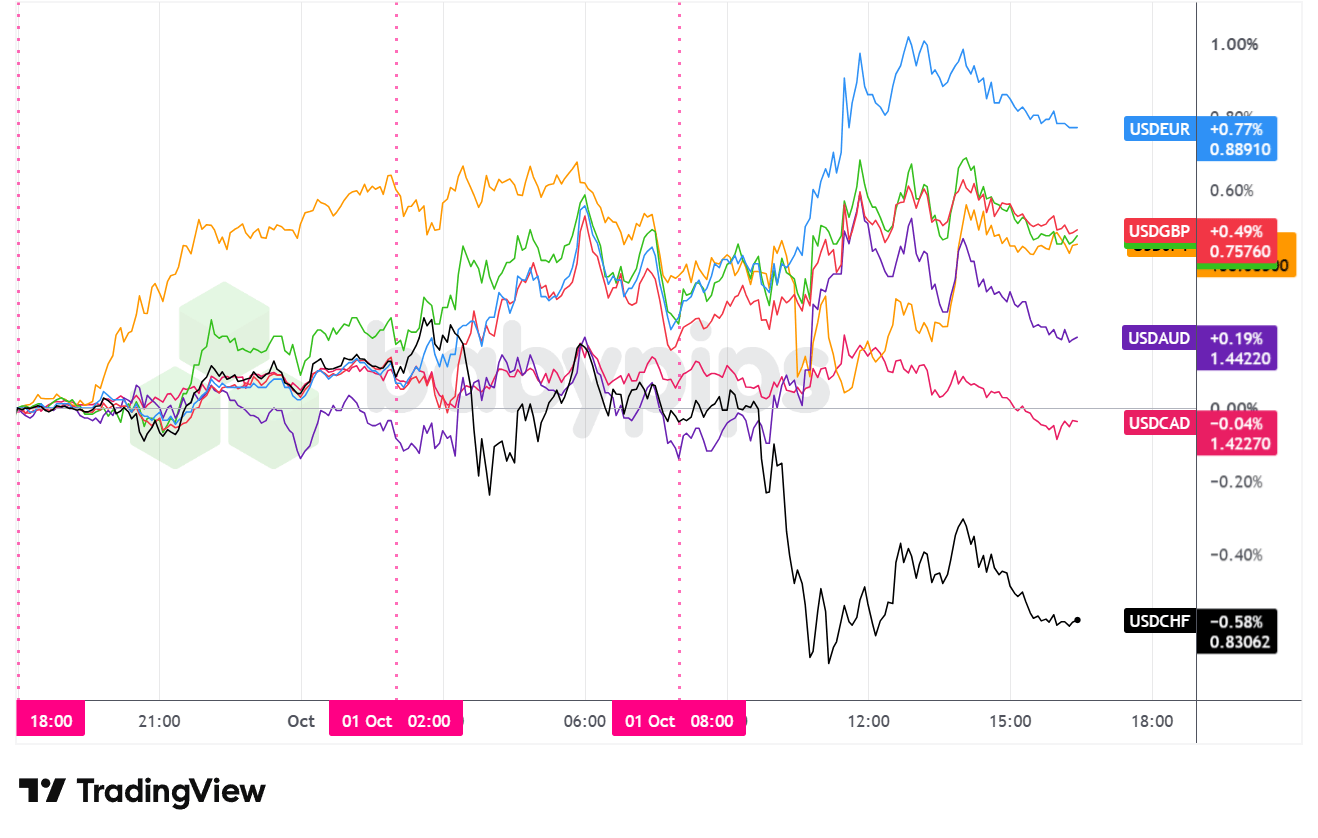
Overlay of USD vs. Major Currencies – Chart Faster With TradingView
The U.S. dollar traded higher against the euro, pound, yen, kiwi and Australian dollar, held flat against the Canadian dollar, and fell against the Swiss franc. The dollar index gained about 0.6% to near 102.0, its highest level in more than three months.
During the Asia session, the dollar traded strongly firmer against the yen and mixed-to-net positive elsewhere. USD/JPY climbed about 0.6% to near 158.40 after the BOJ Summary of Opinions and the Tankan survey arrived around 7:50 pm ET. Some board members said hikes may need to accelerate if prices overshoot 2%, yet the yen weakened, which may mean the market had already priced in that hawkish tilt. The Tankan large manufacturers index rose to 24 from 22. The Australian dollar held steady after manufacturing PMI fell to 49.6 from 52.0, and the other majors held narrow ranges.
The London session brought a firmer dollar as the 10-year yield climbed to 5.34% around 3:25 am ET. The Swiss franc weakened after September inflation printed 0.0% m/m against 0.2% expected at 2:30 am ET, with USD/CHF edging up to 0.8376, and regained ground as equities fell, which may reflect haven demand. The euro and pound showed little reaction to final manufacturing PMIs of 52.9 for the euro area and 51.9 for the U.K. EUR/USD broke below 1.1300 and touched 1.1265, a three-month low, around 6:00 am ET, when the dollar hit session highs against the pound, kiwi and Australian dollar.
The U.S. session opened with the dollar easing slightly against every major. From about 10:30 am ET, the franc and yen gained on the dollar while the euro, pound, Australian dollar and kiwi weakened. The split coincided with the S&P 500 sliding to its low near 11:05 am ET after the ISM prices jump. That mix may reflect haven buying alongside pressure on risk-sensitive currencies. French fiscal worries, with a 2027 budget in the works that includes €54 billion in savings, may have weighed on the euro as EUR/USD slid toward 1.1220 around 12:50 pm ET. By 2:00 pm ET the dollar had recovered to near 158.20 against the yen and the dollar index had reached its high near 102.20, while the 10-year yield bounced from 5.21% to near 5.25%.
In late trading, the dollar led gains against the euro (about 0.8%), followed by the pound, yen and kiwi (about 0.5% each), with a smaller gain versus the Australian dollar (about 0.2%). USD/CAD held near unchanged, and USD/CHF lost about 0.6%, which made the Swiss franc the strongest major.
Upcoming Potential Catalysts on the Economic Calendar
- ANZ Roy Morgan Consumer Confidence for September 2026 at 9:00 pm GMT
- Japan Unemployment Rate for August 2026 at 11:30 pm GMT
- Japan Tokyo CPI for September 2026 at 11:30 pm GMT
- Japan Core CPI for September 2026 at 11:30 pm GMT
- Euro area CPI Growth Rate Flash for September 2026 at 9:00 am GMT
- U.S. Employment Situation Update for September 2026 at 12:30 pm GMT
- U.S. Factory Orders for August 2026 at 2:00 pm GMT
- Fed Logan Speech at 2:00 pm GMT
Japan releases Tokyo CPI overnight, and the data could shape pricing for the next BOJ hike after Thursday’s Summary of Opinions.
Eurostat publishes flash CPI in the European morning, ahead of the U.S. jobs report at 8:30 am ET, where economists expect payrolls to rise by around 90,000 and the unemployment rate to hold at 4.1%. A stronger print may push the 10-year yield back toward Thursday’s 5.34% peak and support the dollar, while a weak number could ease pressure on bonds and equities.
Fed’s Logan speaks at 10:00 am ET, and oil traders will watch for any movement in the stalled US-Iran talks.
Today’s recap shows exactly what happens when major economic data surprises the market, not just how price moves, but the specific sequence of events across forex, equities, bonds, and commodities that most traders miss. Premium members can read our lesson:
📖 From Data to Price Action: What Happens When Big News Hits
Reading this helps you understand the multi-stage price action following data surprises, how asset classes coordinate those moves, and which traps catch unprepared traders.
And if you’re not a Premium subscriber yet, now’s a good time to sign up.
With Babypips Premium, you get full access to School of Pipsology lessons that help you understand not just what the charts show, but the underlying mechanics driving each move across all markets.