

Oil set the tone on Tuesday, which was a relatively quiet session. WTI crude swung from an early gain to a sharp drop after reports pointed to possible de-escalation in the Iran conflict, pulling Treasury yields lower and leaving equities close to unchanged. The U.S. dollar finished a touch firmer against most majors, with the Canadian dollar the weakest link as crude sold off.
Check out the forex news and economic updates you may have missed in the latest trading session!
News Headlines & Data:
- Swiss Current Account for June 30, 2026: 23.7B (10.8B forecast; 15.5B previous)
- U.K. CBI Industrial Trends Orders for September 2026: -9.0 (-40.0 forecast; -25.0 previous)
- U.S. ADP Employment Change Weekly for September 5, 2026: 20.0k (16.25k previous)
- Euro area Consumer Confidence Flash for September 2026: -16.5 (-17.0 forecast; -15.5 previous)
Broad Market Price Action:
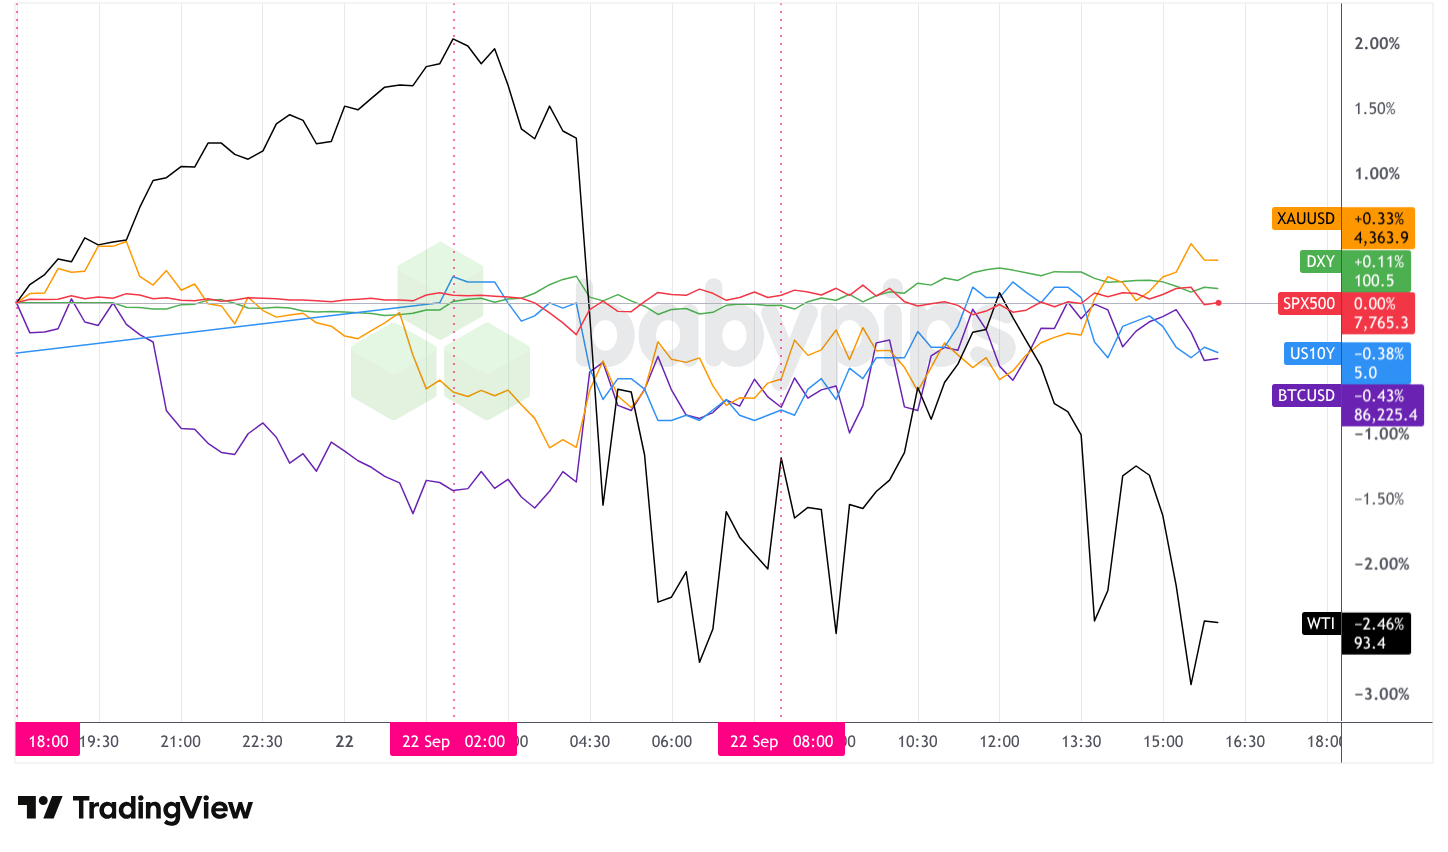
Dollar Index, Gold, Oil, S&P 500, U.S. 10-yr Yield, Bitcoin Overlay – Chart Faster With TradingView
WTI crude did most of the moving. Prices climbed close to 2% during the Asia session, a first gain in five days, without an obvious trigger. The picture changed in London hours, when reports that Iran had offered to reopen the Strait of Hormuz sent crude tumbling, and word that Saudi Arabia stood ready to resume exports from Yanbu deepened the slide. A later denial from Iranian state media clawed back part of the drop, though crude stayed heavy through the U.S. session and settled near $93.40, down roughly 2.5%. The whipsaw played out against a tense backdrop at the UN General Assembly, where Trump warned he could annihilate Iran without a deal even as diplomatic channels stayed open.
The 10-year Treasury yield followed oil lower, slipping from near 4.98% toward 4.93% in London before steadying close to 5.0% into the close. A softer crude price eases near-term inflation pressure, which may help explain the pullback in yields.
The S&P 500 went almost nowhere, closing near 7,765 for a flat session. Strength in chipmakers pushed the tech side of the market toward record territory, while weakness in bank shares pulled the other way, and the two roughly cancelled out at the index level.
Gold firmed a little, ending near $4,360 after a dip into the mid-$4,300s during Asia hours. Bullion spent the day between roughly $4,300 and $4,370, with the recovery building through the U.S. session.
Bitcoin slipped about 0.4% to around $86,000, easing during Asia trade before recovering alongside broader risk appetite. With no crypto-specific catalyst on the day, the move looked tied to the same de-escalation optimism that steadied stocks and pressured oil.
Promoted: Today’s session rewarded whoever could act without all the facts. Crude oil swung from a gain to a sharp drop on an unconfirmed report that Iran might reopen the Strait of Hormuz, then clawed back part of the move once Iranian state media denied it. Waiting for certainty meant missing the move.
In “Thinking in Bets” (4.3⭐ on 5.3K reviews on Amazon), former poker champion Annie Duke reveals why great decisions don’t always yield great outcomes. By treating every trade as a “bet” and weighing probabilities rather than waiting for guarantees, you’ll cut the knee-jerk reactions that headline-driven sessions like this one punish. Learn to embrace uncertainty, separate luck from skill, and execute with calm confidence.
Develop a probabilistic mindset with “Thinking in Bets” by Annie Duke!
Disclosure: We may earn a commission from our partners if you sign up through our links, at no extra cost to you.
FX Market Behavior: U.S. Dollar vs. Majors
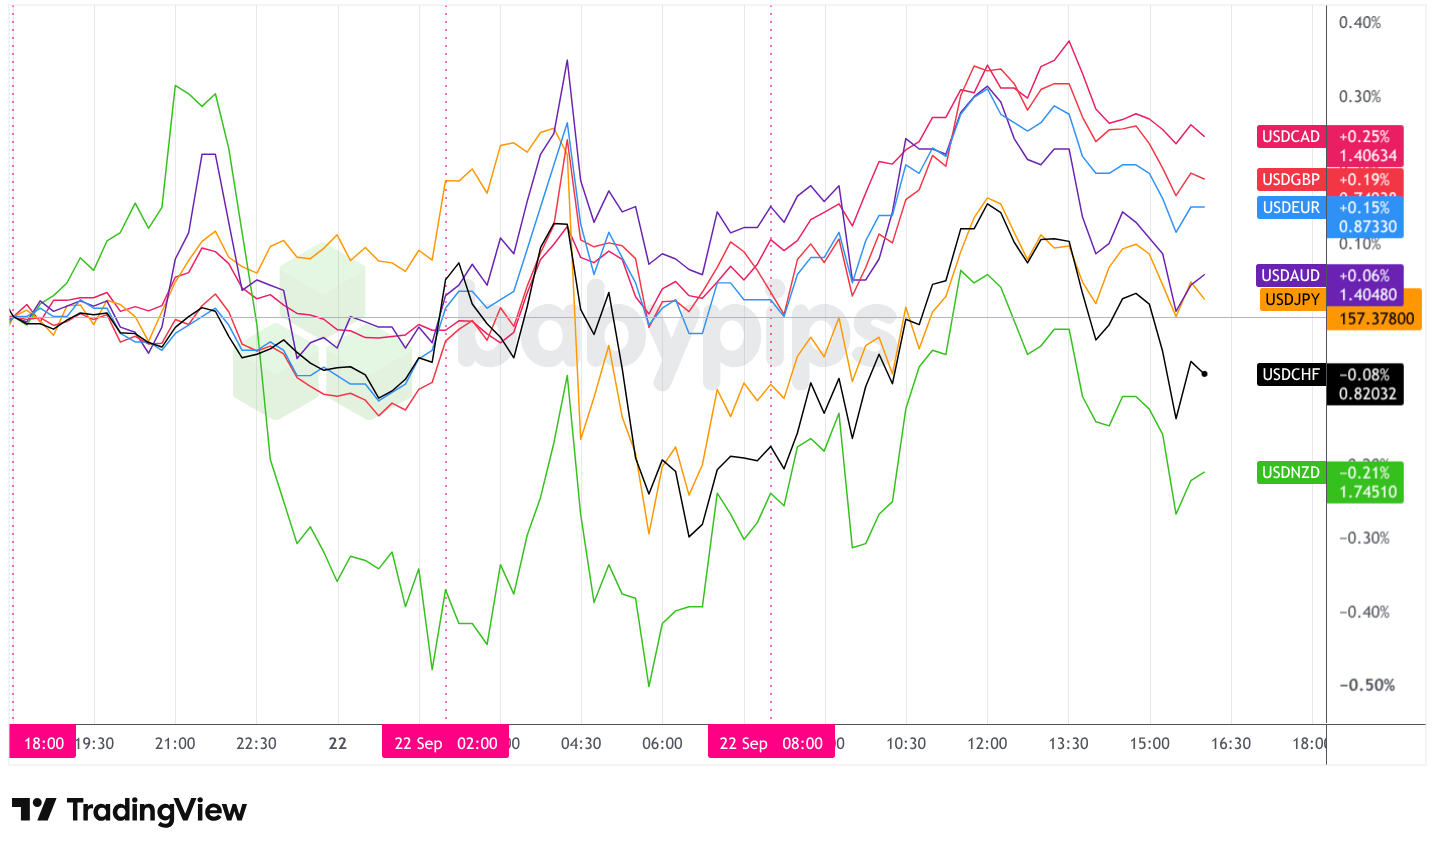
Overlay of USD vs. Major Currencies – Chart Faster With TradingView
The U.S. Dollar Index ended a touch higher near 100.5, up about 0.1%, which masks a choppier path underneath. In thin Asia trade, with Japanese markets shut for a holiday, the dollar gave back modest ground. The New Zealand dollar led the majors after RBNZ Governor Anna Breman said persistent oil prices could lift near-term inflation above the bank’s September assumptions, a hawkish read that supported the kiwi. The Australian dollar found its own footing as RBA Governor Michele Bullock repeated that policy has to address the second-round inflation effects of supply shocks.
The London session flipped the script for crude and rippled into FX. As oil tumbled on the Hormuz headlines, market-implied odds of an October rate hike eased and the dollar handed back its earlier gains. The Swiss franc firmed after a current-account surplus came in well above forecast, nudging USD/CHF lower.
The U.S. session turned the focus back to the UN General Assembly and a run of Fed speakers, and the dollar clawed its way back to finish a hair higher against most majors. The Canadian dollar sat at the bottom of the pack, down with crude, leaving USD/CAD up about 0.25% on the day. At the other end, the kiwi held on as the strongest major.
Upcoming Potential Catalysts on the Economic Calendar
- API Crude Oil Stock Change for September 18, 2026 at 8:30 pm GMT
- Australia S&P Global Manufacturing & Services PMI Flash for September 2026 at 11:00 pm GMT
- Germany S&P Global Manufacturing & Services PMI Flash for September 2026 at 7:30 am GMT
- Euro area S&P Global Manufacturing & Services PMI Flash for September 2026 at 8:00 am GMT
- U.K. S&P Global Manufacturing & Services PMI Flash for September 2026 at 8:30 am GMT
- U.S. MBA 30-Year Mortgage Rate & Applications for September 18, 2026 at 11:00 am GMT
- U.S. S&P Global Manufacturing & Services PMI Flash for September 2026 at 1:45 pm GMT
- U.S. Fed Barr Speech at 2:05 pm GMT
- EIA Crude Oil Stocks Change for September 18, 2026 at 2:30 pm GMT
- ECB Lane Speech at 4:30 pm GMT
- U.S. President Trump and President Xi Summit
- Canada CFIB Business Barometer for September 2026
The next 24 hours hinge on two threads that ran through Tuesday. Flash PMIs across Germany, the euro area, the U.K. and the U.S. will test whether growth is holding up as energy costs bite, and a soft set could move rate-hike pricing in a hurry. Oil, for its part, stays hostage to Iran headlines: fresh signs of de-escalation would likely keep crude and yields under pressure, while any re-escalation could send both the other way. The Trump-Xi summit adds a further layer for risk sentiment as the week goes on.
When oil tumbled on Iran de-escalation headlines, the ripple effect moved Treasury yields, equities, gold, and currencies all at once. Most traders miss these connections. Premium members can read our lesson:
📖 What Is Intermarket Analysis?
Reading this helps you understand how moves in one asset class transmit into currency pairs, why oil and yields move together, and how geopolitical events cascade across markets instead of moving them in isolation.
And if you’re not a Premium subscriber yet, consider joining.
With Babypips Premium, you get full access to School of Pipsology lessons that help you understand the connections between oil, bonds, equities, and currencies, so you’re not blindsided when moves in one market suddenly shake your FX positions.